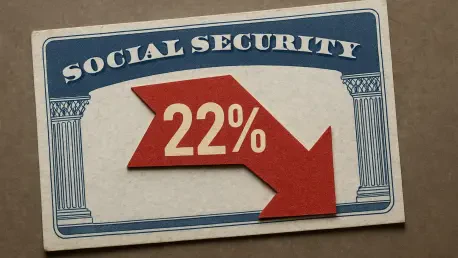
A typical monthly benefit of one thousand nine hundred dollars could drop by over four hundred dollars if the trust fund becomes exhausted. This stark reality underscores the fragility of a system once considered the unwavering bedrock of American retirement. As of 2026, the demographic shift has accelerated, with the baby boomer generation fully transitioning out of the workforce. This labor contraction has created a significant strain on the Social Security Administration, as the ratio of contributing workers to beneficiaries continues to tilt unfavorably. The economic implications extend beyond individual households, influencing broader consumption patterns and national fiscal policy. While the program has faced challenges in the past, the current trajectory requires an immediate reassessment of personal financial roadmaps. Navigating this era of uncertainty demands a clear understanding of the legislative triggers and economic pressures that have brought the trust fund to its current state.
The Mechanics: Understanding the Looming Deficit
The current funding shortfall is primarily driven by the depletion of the Old-Age and Survivors Insurance Trust Fund, which acts as a financial buffer. Projections indicate that this reserve may be exhausted by 2032, leaving the system to rely solely on incoming payroll tax revenue. This transition marks a pivotal moment, as the surplus accumulated over decades is rapidly being utilized to meet the needs of an aging population. The mathematical gap between tax receipts and benefit obligations is widening, creating a structural deficit that requires intervention.
It is essential to distinguish between trust fund exhaustion and total insolvency. Social Security operates on a pay-as-you-go basis, collecting revenue through Federal Insurance Contributions Act taxes from the current workforce. Without the trust fund buffer, the system can only distribute what it receives in real-time. This dynamic leads to the projected 22% reduction, as incoming revenue covers only 78% of promised benefits. This situation remains a legal requirement rather than a choice for the administration.
Workforce Resilience: Strategies for Younger Professionals
For individuals currently in the middle of their professional lives, the prospect of benefit reductions necessitates a shift toward self-funded retirement accounts. Relying on employer-sponsored 401(k) plans and Individual Retirement Accounts has become the primary method for building long-term financial security. By maximizing contributions and ensuring they capture the full extent of employer matching programs, workers can create a significant secondary income source. This approach reduces the reliance on government programs and provides a margin of safety.
Furthermore, younger professionals are encouraged to maintain an aggressive investment posture to combat the eroding effects of inflation. Allocating a larger percentage of a portfolio to equities allows for capital appreciation that historically outpaces the growth of fixed-income assets. While market volatility remains a constant factor, the extended time horizon available to those years away from retirement provides the opportunity to recover from downturns. The goal is to view Social Security as a supplemental benefit rather than the cornerstone of a retirement plan.
Strategic Refinement: Advice for Near-Retirees
Individuals within ten years of their anticipated retirement date face a more compressed timeline for adjustment. Utilizing catch-up contribution provisions, which allow those aged 50 and older to exceed standard investment limits, is a critical step in bolstering savings. These additional funds can significantly enhance the compounding power of a portfolio during the final years of high earning potential. This phase of planning focuses on narrowing the gap between current savings and the projected income needed to maintain a comfortable standard of living.
Beyond savings, lifestyle optimization offers a powerful tool for near-retirees looking to reduce their future financial burden. Evaluating housing needs and potentially downsizing can eliminate high maintenance costs, property taxes, and utility bills. The capital realized from the sale of a larger family home can be reinvested into liquid assets, providing an additional layer of protection. This proactive reduction of fixed expenses ensures that a potential 22% cut in monthly benefits has a less dramatic impact on an individual’s day-to-day quality of life.
Economic Sustainability: Tactics for Current Beneficiaries
Retirees currently receiving benefits must adopt a strategy of operational efficiency to navigate potential volatility in their monthly checks. This involves a meticulous audit of recurring expenses, such as insurance premiums, cellular service contracts, and subscription fees. Small adjustments in discretionary spending can aggregate into a meaningful financial buffer over time. Additionally, the proliferation of the gig economy and remote consulting has provided new avenues for seniors to supplement their income without the physical demands associated with traditional labor roles.
To further enhance stability, shifting remaining assets toward income-producing vehicles is a prudent move for many seniors. This strategy involves prioritizing dividend-paying stocks, high-yield bonds, and Real Estate Investment Trusts that provide regular cash distributions. Unlike growth-oriented stocks, these assets offer a predictable stream of revenue that can help replace the missing portion of a reduced Social Security check. By diversifying income sources, current beneficiaries can maintain their independence and manage their financial affairs with greater confidence.
Actionable Steps: Adapting to Financial Realities
The landscape of American retirement changed as individuals recognized the need for greater self-reliance. This period was defined by a transition away from a singular focus on government-sponsored safety nets toward a more holistic view of personal wealth management. Successful households implemented diversified investment strategies and maintained flexible spending habits to mitigate the risks associated with the trust fund deficit. Those who took early action avoided the most severe consequences of the 22% reduction by building robust private portfolios that functioned independently.
Financial professionals recommended that all citizens treat the potential benefit cut as a definitive scenario rather than a distant possibility. This proactive stance empowered retirees to secure their futures through a combination of tax-advantaged savings and strategic asset allocation. By the time the trust fund reached its exhaustion point, the prepared population had already established alternative income streams. The evolution of the retirement system necessitated a new level of fiscal responsibility, ensuring that financial independence remained achievable despite shifting policies.